
An Irish LTD can protect personal assets, but it also creates recurring filing, tax, disclosure and director obligations that don't apply in the same way to a sole trader. The compliance cost can include a EUR 20 annual return fee, late charges of EUR 100 plus EUR 3 per day up to EUR 1,200, and the possible loss of audit exemption.
The main disadvantages of a limited company in Ireland are therefore practical rather than theoretical. Company money isn't personal money, accounts enter the public register, beneficial ownership information must stay accurate, and directors remain exposed where guarantees, misconduct or statutory breaches apply. The seven disadvantages below follow the LTD lifecycle, from annual compliance to extracting funds and eventually closing the company. Each includes a legal basis, a clearly labelled scenario and a management response. Readers assessing the structure can also review this full sole trader versus limited company comparison before deciding whether the additional obligations fit the business.
What are the disadvantages of a limited company Ireland?
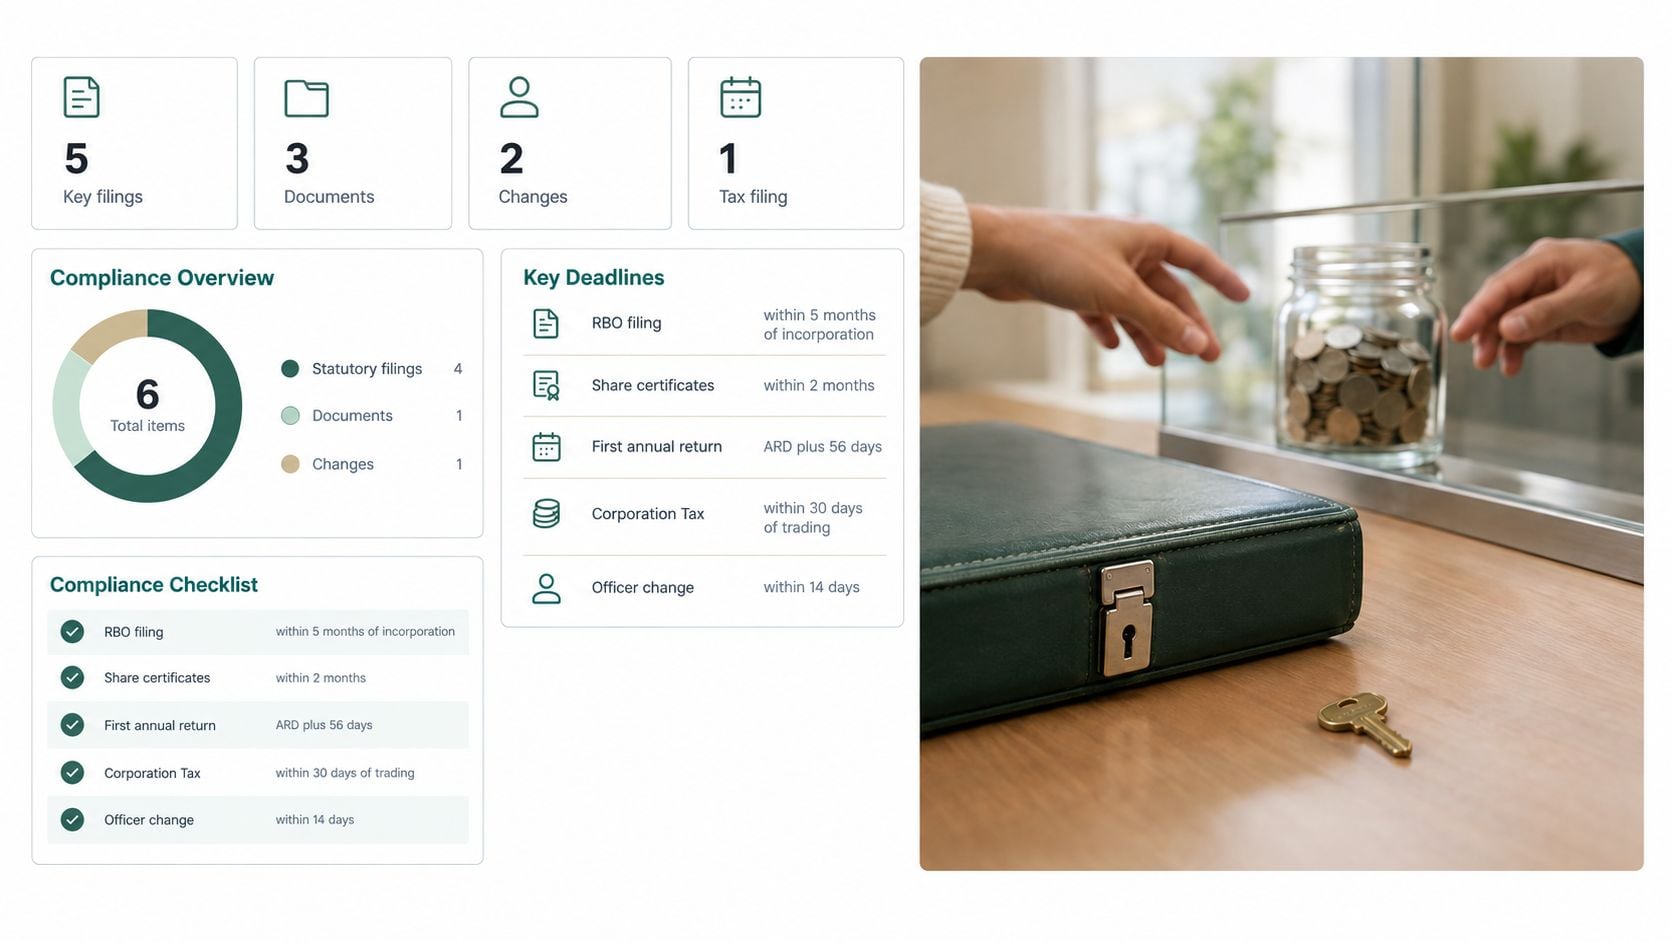
The first disadvantage is that an LTD has a recurring corporate filing cycle even when the business is small or inactive. Section 343 of the Companies Act 2014 requires an annual return, generally filed using Form B1, and the company must attach the required financial statements when applicable.
The first annual return date falls six months after incorporation, and the B1 must then be filed within 56 days of that annual return date. The CRO's electronic filing fee is EUR 20, as set out in its company fees information. The obligation continues each year, so the company needs a calendar rather than a one-off incorporation checklist.
Late filing turns a routine administration task into a direct financial and governance risk. The CRO applies an immediate EUR 100 late fee on the day after the deadline, followed by EUR 3 per day, subject to a maximum late fee of EUR 1,200 per return. Persistent non-filing can contribute to prosecution, involuntary strike-off and possible director disqualification.
How does a missed first B1 deadline affect an Irish LTD?
Example scenario: a director misses the first B1 deadline, which falls six months after incorporation followed by the 56-day filing window. The CRO charge starts at EUR 100 on the next day and increases by EUR 3 per day until the applicable maximum. A second late filing within the relevant period can create a much larger consequence than the fee itself.
Audit exemption: never hedge. Section 363, as amended from 16 July 2025 by S.I. No. 325 of 2025, applies a two-strike test: the exemption is lost for the next two financial years where the annual return is late AND the company also filed late within the preceding five years; a late first return after incorporation is disregarded. The CRO guidance on missed annual returns and the 2025 audit exemption regime explain why a filing error can create a multi-year reporting burden.
Practical rule: prepare the accounts early, set reminders well before the 56-day window expires, file online before the final day and retain the electronic submission evidence.
A filing calendar should identify the annual return date, the accounts preparation date and the internal approval date. Directors managing several companies should keep one consolidated schedule and ensure that accounting records are available before the filing window opens. Where non-resident founders use a formation provider, the Non-Resident Company Formation package is described as covering the first annual return among its formation-related tasks, but later annual compliance remains an ongoing company responsibility.

How much privacy does an Irish LTD lose through public filing?
An Irish LTD doesn't keep its financial statements private in the way an individual business owner may expect. Financial statements filed with the annual return become available through the public CRO register, subject to the filing category and exemptions that apply to the company.
The information visible can include accounts and accompanying notes. The precise level of detail depends on the applicable company size and filing exemptions, so directors shouldn't assume that every company publishes identical information. The important point is that information submitted to the CRO should be treated as information that may be reviewed by competitors, customers, suppliers, lenders and potential commercial partners.
That creates a commercial disadvantage even where the accounts are accurate. A customer may use filed information to assess stability, a supplier may consider payment risk, and a competitor may obtain insight into the company's reported performance. Public filing can also make changes in the company's financial position easier to compare over time.
Can an Irish company keep its accounts confidential?
Example scenario: a small consultancy qualifies for a permitted filing exemption and assumes that the exemption makes its accounts private. It doesn't. The exemption may reduce the information filed, but the information that is filed remains available on the register.
Directors should identify the correct filing category before approving the accounts, prepare the statements accurately and review the material that will become public. The guide to what stays private on the Irish company register can help separate information that must be filed from information that isn't generally placed on the public record.
A practical response is to avoid relying on confidentiality as a competitive strategy.
- Check the filing exemption: Ask an accountant which exemption applies to the company's facts.
- Review the accounts: Understand what customers, suppliers and lenders may see before approval.
- File accurately: Corrections and inconsistent disclosures can create additional questions.
- Plan commercial communications: Explain performance and funding where necessary rather than assuming the public record will remain unnoticed.
A ready-made company with an active VAT registration is a separate formation product, not a privacy solution. The Ready-Made Irish Company with VAT description refers to an active, VIES-registered Irish VAT number, but public company filing obligations still apply after acquisition.

Why can't a director treat company cash as personal money?
The company bank account belongs to the company, even where one director owns all its shares. This is often the disadvantage that catches founders off guard because ownership doesn't turn corporate cash into personal cash.
Money can generally leave through salary processed through payroll, a properly declared dividend, or a documented director's loan, subject to the legal and tax rules applying to the transaction. Section 239 of the Companies Act 2014 restricts certain loans and credit transactions involving directors, while section 438 of the TCA 1997 contains tax provisions affecting loans or benefits involving close companies.
Dividends also have a separate personal tax consequence. Dividend withholding tax is deducted at 25 per cent, and the company's corporation tax treatment depends on the nature of its income. The 12.5 per cent corporation tax rate applies to trading income only, while passive income is taxed at 25 per cent. A proprietary director receives the Earned Income Tax Credit, up to EUR 2,000 in 2026, instead of the Employee Tax Credit, according to Revenue guidance.
What happens if a director urgently needs company money?
Example scenario: a director needs EUR 5,000 urgently during the second month of the financial year. The director cannot transfer the amount directly for personal spending. Salary requires payroll treatment, a dividend requires the relevant corporate documentation and distributable basis, and a loan needs proper records and must be assessed under the company law and tax rules.
The correct route depends on the company's accounts, cash position and the director's personal circumstances. The director's loan account guidance explains the record-keeping issue, while the guide to paying a director by salary or dividends sets out the different extraction routes.
A separate director's loan account should be reconciled regularly. Salary should run through payroll, dividend decisions should be documented, and an accountant should be consulted before choosing a route based on personal figures. The safest working rule is simple: company cash remains company cash until a lawful, documented extraction occurs.
When can an Irish director become personally liable?
Limited liability separates company debts from the director's personal assets, but it isn't an absolute shield. Section 228 of the Companies Act 2014 codifies directors' fiduciary duties, including the duty to act in good faith in the company's interests and to exercise care, skill and diligence.
Personal exposure can arise through misconduct, statutory breaches, reckless or fraudulent trading under section 610, and restriction or disqualification proceedings. A director can also assume personal liability by signing a guarantee. Banks and landlords commonly ask directors to guarantee company obligations, and that guarantee can expose personal assets even though the underlying contract is with the company.
The distinction matters. A director isn't automatically personally liable for every company debt or every filing error. The risk increases where the director acts improperly, continues trading in circumstances requiring professional advice, breaches duties or voluntarily promises to pay the company's obligations.
Which records help protect a director?
Example scenario: a company faces falling cash reserves and a major contract decision. The director approves the transaction without recording the financial information considered, ignores conflicts and signs a personal guarantee without reviewing its terms. If the company later fails, the limited liability analysis will involve more than the company's unpaid invoices.
Directors should maintain board records for significant decisions, disclose conflicts in writing and monitor solvency using timely financial information. The Irish director duties and responsibilities guide provides further context.
- Record decisions: Keep minutes showing the information considered and the decision reached.
- Disclose conflicts: Identify personal interests before the board approves a transaction.
- Review guarantees: Obtain independent legal advice before signing personal obligations.
- Monitor solvency: Seek professional help if the company may not be able to pay its debts.
- Keep filings current: Organised accounts and statutory records support responsible governance.
A director's role is therefore an ongoing responsibility, not merely an appointment made during incorporation.
Why must an Irish LTD keep its beneficial ownership information current?
RBO compliance is separate from the annual return. An Irish company must identify its beneficial owners, report the relevant information and keep that information accurate when ownership or control changes.
The practical burden is greatest where ownership isn't straightforward. A share transfer, an indirect holding company, a change in control or a change to a beneficial owner's residential details can require the company to revisit its analysis and records. The company should maintain an internal share register that connects legal ownership with the people who ultimately own or control the company.
How should an LTD manage changes in beneficial ownership?
Example scenario: an individual transfers shares to a holding company. The legal shareholder changes, but the company must still analyse who ultimately controls or benefits from the structure. Treating the share transfer as the end of the task can leave the RBO information inaccurate.
The step-by-step RBO filing guide explains the filing process. The company should also keep evidence supporting its beneficial ownership analysis, particularly where trusts, layered ownership or indirect control are involved.
- Maintain the share register: Record legal ownership and changes promptly.
- Create a change trigger: Require a review after every share transfer or control change.
- Review governance records: Include RBO accuracy in annual company administration.
- Retain supporting evidence: Keep documents showing how beneficial ownership was identified.
- Use professional support: Speak to an accountant or solicitor where ownership is complex.
The disadvantage is the continuing nature of the obligation. Incorporation doesn't complete beneficial ownership compliance permanently, because ownership and control can change after the company starts trading.
When can a close company face a surcharge on retained passive income?
A close company can face an additional tax charge where it retains certain income instead of distributing it. Section 440 of the TCA 1997 applies to undistributed estate and investment income of an Irish resident close company, while section 441 addresses certain professional service company income.
The distinction between income types is essential. The 12.5 per cent corporation tax rate applies to trading income, whereas passive income is taxed at 25 per cent, as explained in Revenue's corporation tax guidance. A company holding rental, investment or other passive income shouldn't assume that the trading rate applies merely because the entity also operates a trade.
What should a company do before retaining rental or investment income?
Example scenario: a small private company earns rental or investment income and retains the profit to fund a future purchase. The directors should assess close-company status, classify the income correctly and consider whether section 440 applies before assuming that retention produces the expected result.
The same caution applies to certain professional service companies under section 441. The company may need to model distributions, reserves and cash requirements before the accounting period ends. This isn't a recommendation to distribute or retain funds, because the appropriate treatment depends on the company's facts.
Retained cash is a business decision, but retained passive income can also be a tax classification issue.
The management response is to classify each income stream, assess whether the company is close, keep records of distributions and speak to an accountant before leaving passive or professional-service profits in the company. Directors should not apply the trading corporation tax rate to every type of company income.
Why is closing an Irish LTD more involved than stopping trading?
Stopping trading doesn't automatically close an Irish LTD. The company continues to exist until it is removed from the register or wound up, and it may still have annual returns, accounts, tax filings, assets, liabilities and records to deal with.
Voluntary strike-off using Form H15 is intended for a company that meets the statutory conditions and has brought its filings up to date. The CRO filing fee for Form H15 is EUR 15, as shown in the CRO company fees information. The statutory charge is separate from any professional work required to prepare final accounts, settle liabilities or address tax matters.
Is voluntary strike-off suitable where a company still has assets?
Example scenario: a director stops trading while the company still owns equipment or stock, owes money to suppliers and has open tax matters. Ceasing invoices alone doesn't resolve those matters. The company may need to deal with the assets and liabilities first, and a solvent company with material assets may require a members' voluntary liquidation rather than a straightforward H15 application.
A compliant exit should be planned before the company accumulates unresolved obligations.
- Check the conditions: Confirm that the company qualifies for voluntary strike-off before filing Form H15.
- Clear the records: Bring annual returns, accounts, tax filings and RBO information up to date.
- Deal with assets: Transfer or dispose of remaining assets transparently.
- Settle liabilities: Address creditors and outstanding tax obligations before closure.
- Obtain advice: Speak to an accountant or insolvency practitioner where assets or liabilities remain.
Closure is therefore another compliance stage, not an administrative afterthought.
7-Point Comparison: Disadvantages of Irish Limited Companies
| Item | Implementation complexity | Resource requirements | Expected outcomes | Ideal use cases | Key advantages |
|---|---|---|---|---|---|
| Mandatory annual return filing and associated penalties for late submission | Medium, recurring statutory process with strict deadlines and online B1 filing windows | Accounting time, records, CRO online filing (EUR 20), filing calendar and evidence of submission | Compliance if timely; automatic fines (EUR 100 + EUR 3/day up to EUR 1,200); possible loss of audit exemption under two‑strike test; risk of strike‑off/prosecution if persistent | Any Irish LTD required to file annual returns | Predictable statutory process; clear penalty regime encourages timely compliance |
| Public disclosure of financial statements and business performance | Low–Medium, prepare accounts to match applicable filing exemption and review before filing | Accountant review, decisions on small/micro exemptions, internal review of publicly visible items | Accounts become publicly searchable on CRO register; visibility to competitors, suppliers, lenders; disclosure level depends on filing category | Companies where public filing is acceptable or exemptions reduce disclosure | Publicly filed accounts can support creditworthiness and transparency with third parties |
| Restricted access to company funds and complex rules for taking money out | Medium, requires payroll, board resolutions for dividends or documented director's loan (s.239) | Payroll processing, board minutes/resolutions, director's loan records, accountant/tax advice; awareness of dividend WHT (25%) and tax rules | Controlled withdrawals only via salary, dividend or documented loan; tax and reporting consequences; urgent EUR 5,000 requires appropriate route and documentation | Proprietary directors planning remuneration and cashflow | Enforces separation of personal/company assets; enables structured, tax‑aware extraction of funds |
| Personal director liability despite limited liability protection | Low–Medium, governance and monitoring duties; avoid misconduct and statutory breaches | Board minutes, conflict disclosures, solvency monitoring, legal advice before guarantees | Limited liability for ordinary debts but personal exposure for breaches, reckless/fraudulent trading (s.610), guarantees, restriction/disqualification risk | Directors needing to manage legal and governance risk | Clarifies director responsibilities and provides legal framework for accountability |
| Ongoing beneficial ownership (RBO) registration and maintenance obligation | Medium, initial identification and ongoing updates for changes in ownership/control | Collection of personal data, maintained share register, governance routine, legal/accountant input for complex structures | Separate, continuous RBO obligation; must keep BO data accurate and update on changes; risk of queries/enforcement for inaccuracies | Companies with indirect ownership, trusts, or frequent transfers | Improves transparency and helps meet AML/registry obligations |
| Close company surcharge on undistributed investment income and deemed corporate profits | Medium–High, requires income classification and tax modelling to assess surcharge exposure | Tax advice, modelling, accurate accounting to distinguish trading vs passive/professional income | Trading income taxed at 12.5%; passive income generally taxed at 25%; retaining certain profits can trigger close‑company rules and surcharges | Private companies with rental, investment or professional‑service income | Clarifies tax impact of retaining passive income and supports informed distribution planning |
| Complexity and cost of company closure and voluntary strike-off requirements | Medium–High, must meet statutory conditions and settle filings, assets and liabilities before dissolution | Up‑to‑date filings, CRO Form H15 fee (EUR 15), accountant or insolvency practitioner where assets/liabilities exist | Proper dissolution if conditions met; Form H15 for qualifying solvent companies; MVL or insolvency processes if assets/liabilities remain; objections or delays possible | Dormant companies with no assets/liabilities (H15); solvent companies with assets requiring MVL | Formal closure routes that limit future obligations when executed correctly |
When do these LTD costs make sense?
The disadvantages of an Irish LTD are spread across the full lifecycle. The company must maintain annual returns and accounts, accept public filing exposure, keep beneficial ownership information current, manage payroll and corporation tax, control access to company cash, assess close-company tax rules and preserve evidence of responsible director decisions. At the end, stopping trade doesn't end the company's obligations, because the company still needs a compliant strike-off or liquidation route.
The most consequential cost is often not the ordinary filing fee. A missed annual return can create late charges, threaten audit exemption under the statutory two-strike test and expose the company to strike-off consequences. The most persistent practical risk is the separation between the director and the company. A director who treats the company account as a personal account can create loan, payroll, dividend and tax problems even where the company is wholly owned by that director.
An LTD may still suit an Irish resident business where commercial risk, retained working capital, investment plans or customer requirements justify the additional administration. That decision should be based on the company's expected profit, the amount required personally, the likelihood of retaining funds and the director's ability to maintain accurate records, not on the corporation tax headline alone. For a broader structure decision, readers can use this guide to choosing between a sole trader and an Irish limited company.
Before incorporating or continuing an existing LTD, the director should map the annual return, accounts, payroll, RBO, corporation tax, extraction and closure responsibilities with an accountant. For an Irish resident founder who has decided that an LTD is appropriate, company formation for Irish residents is one available formation route, but formation doesn't remove the ongoing obligations described above.
This content is general guidance, not legal or tax advice.
Chern & Co, through Chern & Co (RegisterCompany.ie), provides Irish LTD formation services and related administrative support for founders establishing a company in the Republic of Ireland. Visit the site to review the available formation information and consider the compliance responsibilities before proceeding.


